A payroll month produces four sets of journal entries: one to record the salary cost and what is owed to staff and authorities, one for the employer's own pension, NSITF and ITF costs, one when staff are paid, and one when each authority is paid. After the last payment, every payroll liability account should be back to zero, except the ITF accrual, which builds through the year. This guide posts a real month for five employees with a total gross of ₦2,400,000, and shows how to check that your liability accounts agree with what you actually remitted. Your accountant decides your chart of accounts and how to treat items such as group life premiums; the entries below are the standard pattern.
The month we are posting
Five staff at a Lagos consultancy, paid on the 28th. We treat the whole gross as pensionable to keep the figures clear (in a real payroll, pension is on basic, housing and transport, and the numbers would be smaller). PAYE comes from the 2026 bands after the 8% employee pension, calculated with the site's PAYE calculation.
| Employee | Gross | Pension 8% | PAYE | Net pay | Employer pension 10% |
|---|---|---|---|---|---|
| Bola | ₦800,000 | ₦64,000 | ₦114,980 | ₦621,020 | ₦80,000 |
| Emeka | ₦600,000 | ₦48,000 | ₦81,860 | ₦470,140 | ₦60,000 |
| Ngozi | ₦450,000 | ₦36,000 | ₦57,020 | ₦356,980 | ₦45,000 |
| Yetunde | ₦350,000 | ₦28,000 | ₦40,460 | ₦281,540 | ₦35,000 |
| Aisha | ₦200,000 | ₦16,000 | ₦17,600 | ₦166,400 | ₦20,000 |
| Total | ₦2,400,000 | ₦192,000 | ₦311,920 | ₦1,896,080 | ₦240,000 |
NSITF is 1% of total monthly payroll, so ₦24,000. ITF at 1% of annual payroll, if the business qualifies, accrues at ₦24,000 a month. See how pension contributions are calculated for the pension formula, and if you start from a take-home target the sums run the other way.
Entry 1: record the payroll on the 28th
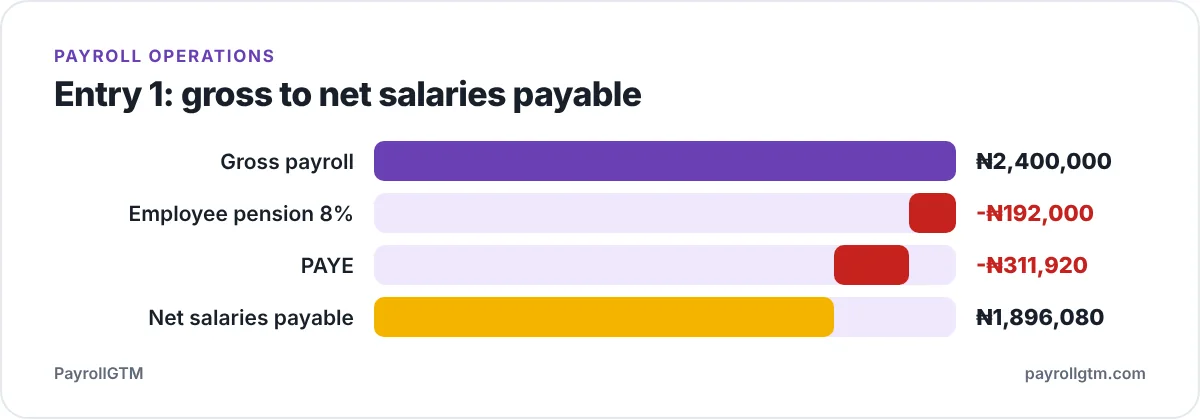
Gross salary is the expense. Everything taken out of it, and the net amount, are liabilities until paid.
| Account | Debit | Credit |
|---|---|---|
| Salaries and wages expense | ₦2,400,000 | |
| PAYE payable | ₦311,920 | |
| Pension payable (employee 8%) | ₦192,000 | |
| Net salaries payable | ₦1,896,080 |
Debits and credits both total ₦2,400,000. If you hold a salary advance or loan recovery for any employee, it would reduce the net salaries payable and credit a staff-receivable account.
Entry 2: the employer's own costs
These costs sit on top of gross pay and are expenses of the business, not deductions from anyone.
| Account | Debit | Credit |
|---|---|---|
| Employer pension expense | ₦240,000 | |
| NSITF expense | ₦24,000 | |
| ITF expense | ₦24,000 | |
| Pension payable (employer 10%) | ₦240,000 | |
| NSITF payable | ₦24,000 | |
| ITF payable (accrual) | ₦24,000 |
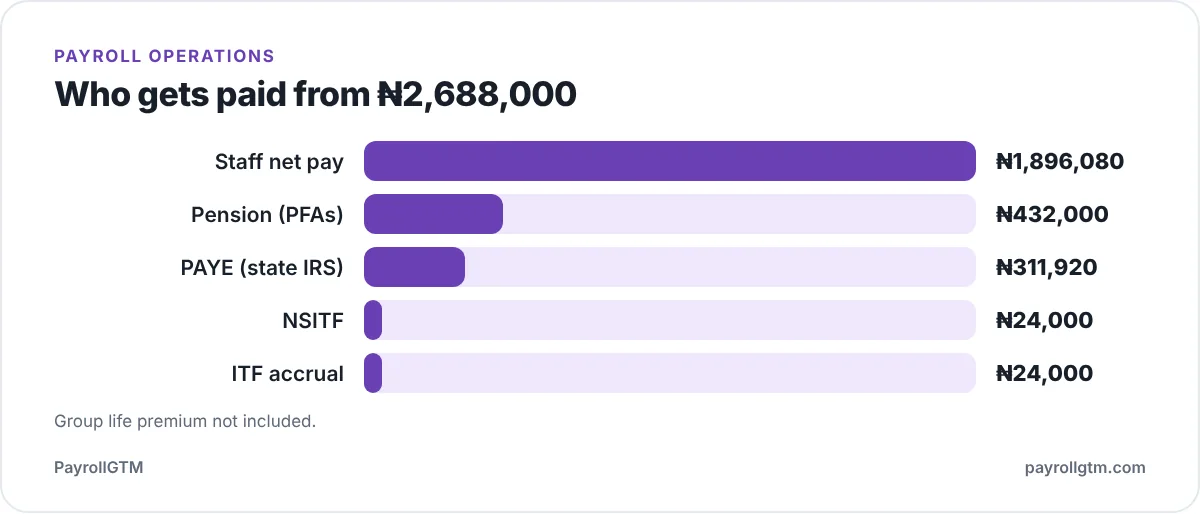
The group life premium is also an employer cost. Its amount depends on your insurer's quote, so we have not put a figure in the example. Usually the premium is paid yearly, booked as a prepayment, and released to expense by a monthly journal. The total cost of the month is ₦2,400,000 + ₦240,000 + ₦24,000 + ₦24,000 = ₦2,688,000, before group life.
Entries 3 and 4: pay staff, then pay the authorities
Staff are paid first, on the 28th, from the bulk transfer described in paying salaries by bank transfer.
| Date | Account | Debit | Credit |
|---|---|---|---|
| 28th | Net salaries payable | ₦1,896,080 | |
| 28th | Bank | ₦1,896,080 | |
| Within 7 working days | Pension payable (₦192,000 + ₦240,000) | ₦432,000 | |
| Within 7 working days | Bank | ₦432,000 | |
| By the 10th of next month | PAYE payable | ₦311,920 | |
| By the 10th of next month | Bank | ₦311,920 | |
| On the NSITF payment date | NSITF payable | ₦24,000 | |
| On the NSITF payment date | Bank | ₦24,000 |
The pension is posted as one ₦432,000 payment, but the bank will usually show several transfers, one per PFA, which is why the reconciliation below matters. The ITF payable is not cleared monthly. The business accrues ₦24,000 a month, so after a full year at this payroll it should hold about ₦288,000 until the annual payment. The NSITF payment date and ITF due date are not set out here: confirm them with the agencies (see NSITF contributions and ITF compliance).
When pay day falls after month-end
If the consultancy paid on the 3rd of the following month instead of the 28th, the work is still done in the earlier month, so Entry 1 and Entry 2 are posted at month-end as accruals. The expense then lands in the month the staff earned it, and ₦1,896,080 shows as net salaries payable on the balance sheet until the 3rd. The payments on the 3rd clear it. Cash-basis bookkeepers who record salary only when the bank moves will show one month with no salary cost and the next with two, which makes profit by month meaningless. The pay-day choice itself is covered in payroll cut-off dates and pay schedules.
Other lines you may need to add
- Voluntary NHF. Only for staff who opted in. It needs its own payable account, credited with 2.5% of basic and cleared when paid to the FMBN.
- Loan and advance recoveries. Debit the staff receivable account, so that the loan balance falls as the deduction is made.
- Bonuses and allowances paid once. These go through the same entry, because they are part of employment income and affect PAYE for the month. See the step-by-step payroll process for where they enter the calculation.
- Staff who are not on payroll. Contractors paid on invoice are not part of these entries. They belong in purchases or professional fees, and no PAYE or pension liability arises in your books for them unless the person is really an employee in law. Misfiling an employee as a contractor is the usual way a payroll liability goes missing from the ledger entirely.
Post the journal from the approved payroll register, not from memory of what the bank file said. Keep the payroll register, the posted journal and the bank statement together for each month. If the state IRS or an auditor asks how your PAYE figure was built, those three documents should agree line by line.
Reconciling the liability accounts
This is the check that catches errors. At the end of the next month, before posting the new payroll, each account should look like this.
| Liability account | Should be | If it is not |
|---|---|---|
| Net salaries payable | Nil | A staff member was not paid, or paid twice. Check the bank file |
| PAYE payable | Nil after the 10th | Any balance is tax deducted and not remitted, a penalty risk |
| Pension payable | Nil after the pension deadline | A PFA payment missing, or paid under another employee's PIN |
| NSITF payable | Nil after payment | Payment late or not matched to the right month |
| ITF payable | 12 months of accrual | Accrual forgotten in some months |
Match each payment to its bank line and a receipt. The full routine for this check is in the monthly payroll reconciliation checklist.
Errors that show up in the journals
- Posting net pay as the expense. If the accountant debits only the ₦1,896,080 that left the bank, the salary expense is understated by ₦503,920 (₦311,920 PAYE plus ₦192,000 employee pension), and the liabilities never appear. The profit looks better than it is and the tax and pension debts are invisible.
- Leaving the employer's costs out. The ₦288,000 of employer pension, NSITF and ITF for the month is as real as the salary.
- Lumping PAYE and pension into "deductions payable". One account cannot be tied to two different payees. Keep separate accounts.
- Posting corrections to the wrong month. A late raise or a missed allowance is handled as a catch-up in the next payroll, as explained in back pay and salary corrections. A part-month start or exit follows prorating salary for part of a month.
Journals also help against fraud. A payroll total that jumps with no hiring, or a net salaries account that does not clear, is the first sign of a ghost worker, and how to prevent payroll fraud shows what else to check.