Nigeria PAYE & Net Pay Calculator
Estimate monthly PAYE, pension and take-home pay under the Nigeria Tax Act 2025 (in force since 1 January 2026), with every band shown so you can check the working.
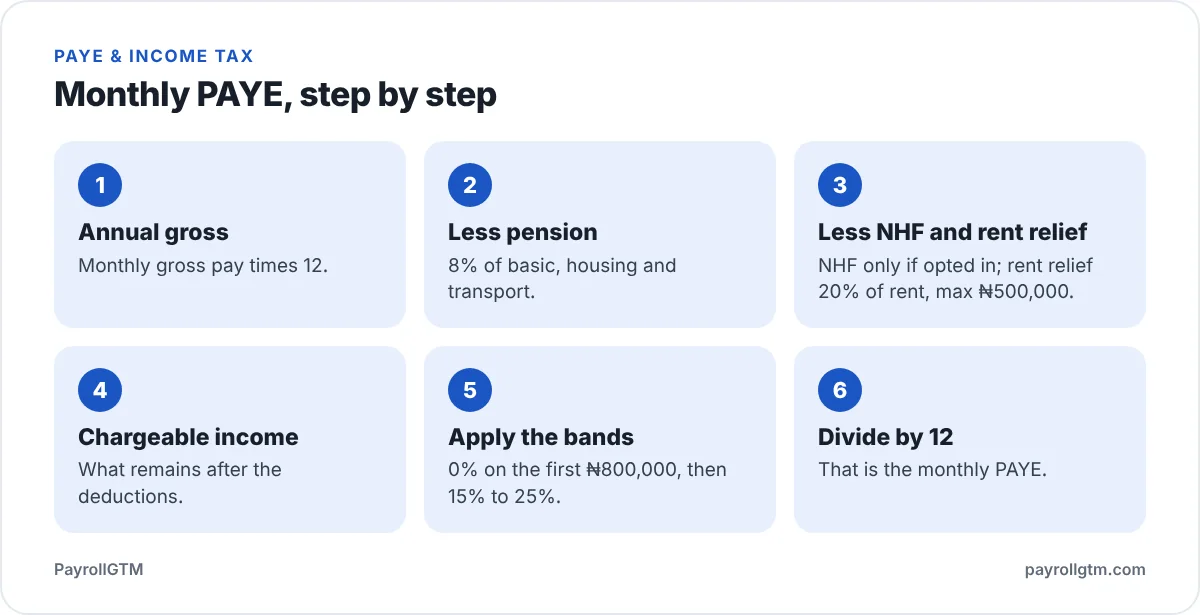
How this calculator works
The calculator follows the personal income tax rules of the Nigeria Tax Act 2025, which replaced the Personal Income Tax Act from 1 January 2026. It annualises your monthly figures, removes the allowable deductions, applies the progressive bands, and divides the result by twelve.
- Gross pay is basic salary plus housing, transport and any other taxable allowances.
- Employee pension is 8% of basic, housing and transport, as required by the Pension Reform Act 2014.
- NHF (optional) is 2.5% of basic salary for employees covered by the National Housing Fund scheme.
- Rent relief replaces the old Consolidated Relief Allowance. It is 20% of annual rent paid, capped at ₦500,000.
- Bands apply to what is left: first ₦800,000 at 0%, next ₦2.2m at 15%, next ₦9m at 18%, next ₦13m at 21%, next ₦25m at 23%, and anything above ₦50m at 25%.
The 2026 PAYE bands
| Slice of annual chargeable income | Rate |
|---|---|
| First ₦800,000 | 0% |
| Next ₦2,200,000 (up to ₦3 million) | 15% |
| Next ₦9,000,000 (up to ₦12 million) | 18% |
| Next ₦13,000,000 (up to ₦25 million) | 21% |
| Next ₦25,000,000 (up to ₦50 million) | 23% |
| Above ₦50 million | 25% |
Worked example
An employee earns ₦250,000 a month with no rent relief claimed and the whole amount treated as pensionable. Annual gross is ₦3,000,000 and pension is ₦240,000, leaving ₦2,760,000 chargeable. The first ₦800,000 is tax-free and the remaining ₦1,960,000 is taxed at 15%, giving ₦294,000 a year, or ₦24,500 a month. Take-home pay is ₦205,500.
Limits of this estimate
Other deductions such as NHIS contributions, life assurance premiums or approved pension additions can reduce chargeable income further, and PAYE is remitted to the relevant State Internal Revenue Service, whose assessment is final. Treat the result as an estimate and confirm important figures with a qualified tax professional. See our disclaimer.
Sources
Nigeria Tax Act 2025 (Fourth Schedule for the rate bands), Nigeria Tax Administration Act 2025, and the Pension Reform Act 2014. If you spot a discrepancy, tell us and we will check it against the Act.
Related guides
- How to Calculate PAYE in Nigeria in 2026: Step by Step With Worked Examples
- How to Calculate Pension Contributions in Nigeria (8% Employee, 10% Employer)
- How to Read a Nigerian Payslip: Every Line Explained With a 2026 Example
- PAYE in Nigeria 2026: How Rent Relief Replaced the CRA Under the Nigeria Tax Act