A state IRS payroll audit asks one question: can you prove that the PAYE you deducted, and the PAYE you remitted, match what the law required for every person on your payroll? You pass it by having the documents ready, in order, and by being able to explain every difference between what staff were paid and what you reported. This checklist gets a small employer to that point in about 30 days.
What does a payroll audit actually look at?
Expect questions to come from five places, because those are the documents that can be checked against each other.
- The monthly PAYE schedules and remittance evidence. Names, gross pay, deductions, tax, the date you paid and the receipt.
- Payslips and bank statements. Do the amounts actually paid to staff match the schedule? A gap here is the quickest way to start a deeper review.
- The annual return of emoluments (Form H1). Filed by 31 January for the preceding year under NTAA s.14. Does it agree with the twelve monthly schedules?
- Employment contracts and salary structures. Which part is basic, housing and transport, and which is other allowance? That split drives pension.
- Staff lists. Who is an employee, who is a contractor, and whether someone is being paid outside payroll. See employee or contractor classification.
An auditor may also look at proof for any relief you applied. Rent relief of 20% of rent paid (capped at ₦500,000) needs a tenancy agreement and receipts. A deduction with no paper behind it is a deduction they can disallow.
The document pack to have ready
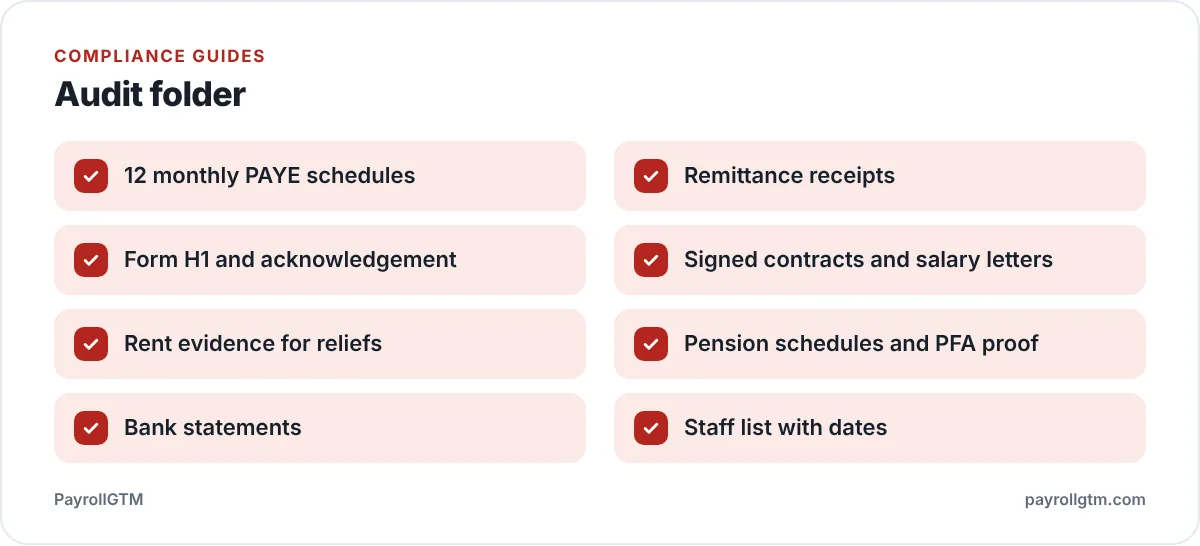
Put it in one folder, physical or shared, labelled by year. If any item does not exist, write down why and what replaced it.
| Document | What it proves | Common gap |
|---|---|---|
| Payroll register, 12 months | Gross, deductions and net per person | Edited spreadsheets with no version history |
| PAYE remittance receipts | Tax paid to the right state IRS | One lump payment covering several staff, no breakdown |
| Form H1 and acknowledgement | Annual return filed on time | No proof of submission |
| Signed contracts and salary letters | Basic, housing, transport split | Unsigned or outdated letters |
| Rent evidence on file | Basis for rent relief claimed | Relief applied, receipts never collected |
| Pension schedules and PFA proof | Contributions on the right base, on time | Base set on basic only |
| Bank statements | Salaries really paid | Cash top-ups outside payroll |
| Staff list with start and exit dates | Nobody missing, nobody extra | Leavers still on the schedule |
The payroll record-keeping guide explains how long to keep each item and how to store it.
A 30-day preparation plan
Do not wait for the notice. Run this when you first hear that a review is possible, or once a year in January.
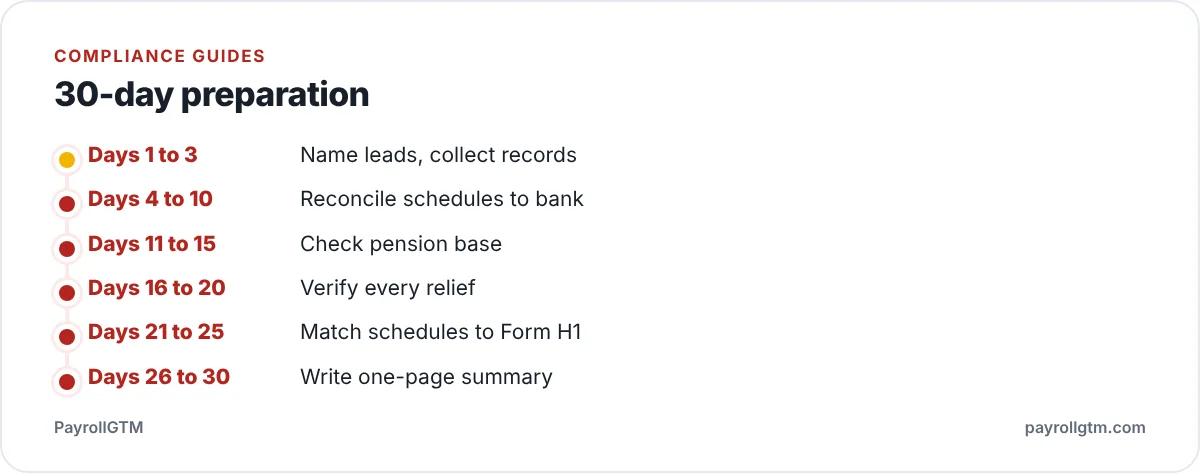
- Days 1 to 3. Name one person to lead and one to approve. Collect the staff list, last 12 monthly schedules and bank statements into the folder.
- Days 4 to 10. Reconcile. For each month, compare the schedule to the bank payments. List every difference and its cause. The annual payroll audit checklist goes through this internally.
- Days 11 to 15. Check the pension base against each contract. This is where most findings come from (see below).
- Days 16 to 20. Check every relief. For each person with rent relief, confirm the agreement and receipts are on file. Remove any relief you cannot support, and fix the future months.
- Days 21 to 25. Compare the 12 schedules to Form H1. Check the annual return was filed and you can show it.
- Days 26 to 30. Write a one-page summary of what you found, what you fixed and what is outstanding. Brief the person who will meet the auditor.
If an error turns up, correct it and keep the correction, don't hide it. See penalties for late PAYE and payroll defaults for what late or missing remittances can cost, and confirm current figures with your state IRS.
The mistake auditors find most: the wrong pensionable base
The statutory minimum is calculated on at least basic, housing and transport. Employers often compute it on basic alone, which understates it. Here is what that does for one person.
Correct pensionable pay is ₦200,000 + ₦100,000 + ₦60,000 = ₦360,000. Employee pension at 8% is ₦28,800 and employer at 10% is ₦36,000, total ₦64,800.
If payroll used basic only (₦200,000), the contributions are ₦16,000 and ₦20,000, total ₦36,000.
Shortfall: ₦28,800 a month, ₦345,600 a year, for one employee.
The tax is wrong too. Because the pension deduction was too small, Obinna's chargeable income was ₦4,608,000 instead of ₦4,454,400, and annual PAYE was ₦619,440 instead of ₦591,792. He was over-taxed by ₦27,648 a year.
Under the Pension Reform Act the penalty for late remittance is 2% of the unremitted contribution for each month of delay, so the shortfall grows the longer it sits. Fix the base now, pay the arrears to the RSAs and keep proof. Our common payroll mistakes list shows other findings to look for.
If you receive a notice or demand
- Note the date you received it and the deadline in the letter. Diarise it.
- Reply in writing and on time, even if only to confirm receipt and ask for any extra time you need. Silence is the worst answer.
- Answer only what was asked and attach copies, never your only original.
- Keep the tone factual and polite. Do not argue about the auditor.
- If the claimed amount looks large or wrong, ask for the workings, then check them against your records.
- Involve your accountant or a tax adviser before agreeing a figure or a payment plan.
Whether you can object, and how, is governed by the Act and by your state's process, so ask in writing what route is available before the deadline passes.
Questions to rehearse before anyone arrives
Sit the finance lead and the HR lead down for an hour and ask each other the questions an officer is likely to ask. Why does January's net pay for Tunde differ from the schedule? Which employees live outside this state, and where does their PAYE go? Who left in the year and was their final pay taxed? Why is one person's rent relief higher than another's? Why did total PAYE jump in December (a bonus run, for instance, as in how bonuses are taxed)? If an answer needs "I will check", note it and find out before the meeting, not during it.
Who to involve
The finance lead owns the reconciliation. HR owns contracts and the staff list. The managing director signs off anything that changes a past return. An external accountant is worth the fee when the notice has a number on it. Employee data is personal data: share only what is required and keep it secure, as explained in employee data protection for payroll.
For a company, the annual returns filed with the CAC are a separate regime but sometimes get asked about in the same conversation, so keep your CAC annual return proof in the folder. If your January 2026 setup was never reviewed, the January 2026 employer checklist is the place to confirm you applied the new bands and dropped the old relief.